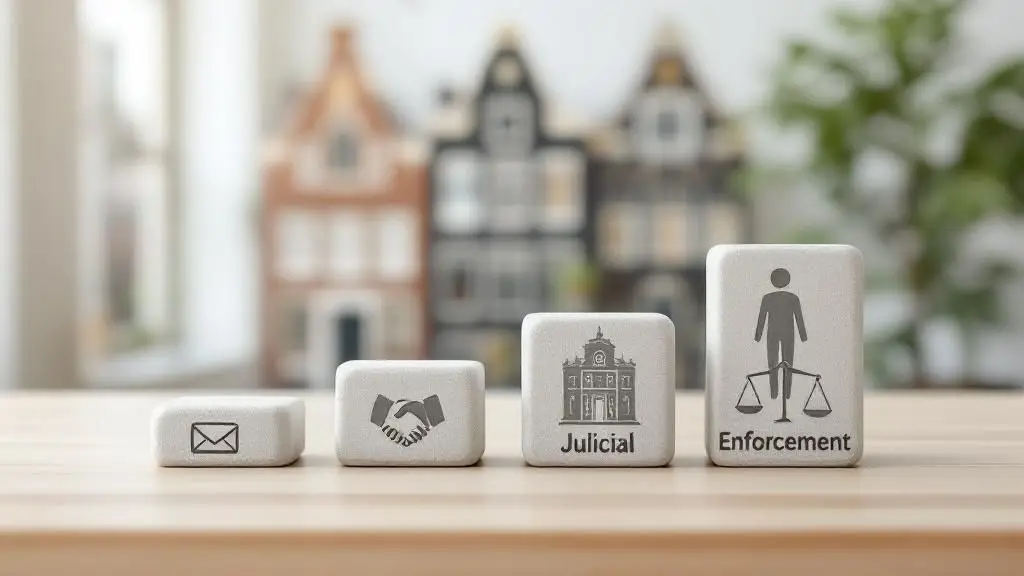
Debt collection in the Netherlands runs in two stages. The amicable stage is everything a creditor does outside court: reminders, a formal notice of default, statutory interest and, against a consumer, a compulsory fourteen-day letter before any collection costs may be charged. The judicial stage starts with a writ of summons served by a bailiff and ends, if the claim succeeds, in a judgment that the bailiff can enforce against wages, bank accounts and assets. A step skipped in the first stage, such as a defective fourteen-day letter, usually costs you money in the second.
Table of contents
When does an unpaid invoice become a claim you can enforce?
An overdue invoice becomes enforceable once the debtor is in default (verzuim). Until then, no statutory interest or collection costs run.
Default usually arises after a written notice of default (ingebrekestelling) under article 6:82 of the Dutch Civil Code, which gives the debtor a reasonable final period to pay. In some situations, listed in article 6:83 of the Civil Code, default arises without any notice. That is the case where the parties agreed a fixed payment date that has passed, where the obligation arises from a wrongful act, or where the debtor makes clear that it will not pay.
Once the debtor is in default, statutory interest runs by operation of law. For consumer transactions the rate is the ordinary statutory interest of article 6:119 of the Civil Code. For commercial transactions between businesses, or between a business and a public authority, the higher statutory commercial interest of article 6:119a applies. Both rates are set by order in council and change periodically. Take the applicable percentage from the government's published figures for each period, not from an old invoice.
Which payment term applies?
Between businesses, where nothing has been agreed, payment is due within thirty days of receipt of the invoice. A longer term may be agreed, but not an unlimited one. A large company may not impose a payment term of more than thirty days on a small or medium-sized supplier. A clause that goes beyond what the law allows is void. The statutory term then applies in its place, and commercial interest runs from the day it expires.

Why is the fourteen-day letter so often wrong?
Against a consumer, extrajudicial collection costs may only be charged after the creditor has sent a specific written reminder under article 6:96 paragraph 6 of the Civil Code. Many letters get the term wrong, and then no collection costs are due at all.
The letter must give the consumer at least fourteen days to pay the principal sum without any collection costs, and it must state what the costs will be if payment is not made. The Supreme Court has held that the fourteen days start on the day after the letter reaches the consumer (Hoge Raad 25 November 2016, ECLI:NL:HR:2016:2704). A letter that counts fourteen days from its own date, or from the day it was sent, therefore does not comply.
The consequence is not a warning: the claim for collection costs simply fails. According to the same judgment, a defective letter cannot be repaired by later granting a little extra time; the creditor must send a new letter that does comply. Courts also test this of their own motion, even if the consumer does not raise the point.
The amount of the costs is fixed by decree on a sliding scale of percentages of the principal. The percentage decreases as the claim grows, and there is a statutory minimum and maximum. That scale is mandatory towards consumers. Towards business debtors the parties may agree different terms in their general conditions, which is one of the few genuinely useful clauses in a set of standard terms.
What rules apply in the amicable phase?
The amicable phase is regulated: collection service providers must be registered and must follow quality rules. Most claims are still resolved in this phase, and it is where the commercial outcome is usually decided.
The phase starts with a reminder, moves on to a formal demand (aanmaning) and, if the debtor responds, often ends in a payment arrangement or a settlement for part of the claim. Being willing to accept instalments frequently brings in more than insisting on the full amount and receiving nothing.
Under the Debt Collection Services Quality Act (Wet kwaliteit incassodienstverlening), collection service providers must be entered in the register of debt collection services kept by Justis. Since 1 April 2025 it is prohibited to carry out or offer extrajudicial collection without that registration. Registered providers must meet requirements on professional competence, the accuracy of the information in their letters, the handling of complaints and the way they contact debtors. The Justice and Security Inspectorate (Inspectie Justitie en Veiligheid) supervises the collection market and can impose fines. According to the government business portal, from 1 October 2026 a debtor does not have to pay the collection costs or interest charged by an unregistered agency; the principal debt remains due.

Who has which powers: collection agency or bailiff?
A collection agency (incassobureau) has no powers beyond those of any other creditor. It can write, telephone and negotiate, but it cannot seize anything.
A bailiff (gerechtsdeurwaarder) is a public official appointed by royal decree. Only a bailiff may serve a writ of summons and levy attachment. A bailiff who acts in the amicable phase, before any judgment, is acting as an ordinary agent and has no more coercive power than an agency. The letterhead does not change that.
When does a claim expire, and how do you stop the clock?
A claim for payment under a contract generally becomes time-barred five years after it fell due, under article 3:307 of the Civil Code. A written demand stops the clock and starts a new period.
Creditors often lose claims to limitation periods that a single letter would have prevented. The five-year period runs from the day after the claim became due and payable. Shorter periods apply in specific cases. In a consumer sale, the seller's claim for payment of the purchase price is time-barred after two years (article 7:28 of the Civil Code). Claims arising from a wrongful act are subject to their own regime.
The period can be interrupted. Under article 3:317 of the Civil Code, a written demand or a written notice in which the creditor unequivocally reserves its right to performance interrupts limitation, and a fresh period starts the next day. Issuing proceedings interrupts it as well. An internal file note does not, nor does a telephone call that is not confirmed in writing, nor a reminder that does not make clear that the creditor still claims payment. Keeping a dated copy of every demand is the cheapest form of litigation insurance available.
Can you prove the claim?
Before any of this matters, the claim has to exist and be provable. The file should show what was agreed, that the goods or services were delivered, that the invoice was sent and received, and which general conditions apply and when they were made available.
Where a claim is disputed on the merits rather than on capacity to pay, it is usually the delivery and the terms that decide the case. Our explanation of what a claim is under Dutch law sets out the elements in more detail.
How can you secure the claim before judgment?
You can ask the court for leave to levy prejudgment attachment (conservatoir beslag). This freezes assets before the claim has been decided, so the debtor cannot move them in the meantime.
Proceedings take time, and a debtor who knows a claim is coming may try to move assets. Dutch law offers an unusually accessible remedy. On a written application, the interim relief judge of the district court can give leave to attach bank accounts, receivables owed to the debtor by third parties, movable goods, shares or immovable property.
The application is normally decided without hearing the debtor, often within days, so the attachment comes as a surprise. Leave is given on a summary assessment of the claim. The judge sets a period, commonly fourteen days, within which the main proceedings must be started. If they are not, the attachment lapses.
A creditor who levies attachment and then loses the case is in principle liable for the damage caused, without the debtor having to prove fault. Read our article on prejudgment attachment in Dutch law before you decide to use it.
Which court hears the claim, and what happens there?
Money claims up to 25,000 euro go to the subdistrict court (kantonrechter), where you do not need a lawyer. Larger claims go to the district court, where a lawyer is compulsory.
Regardless of value, the subdistrict court also hears cases about employment, tenancy, consumer credit and consumer sales. Everything else goes to the ordinary chamber of the district court.
The distinction has a direct effect on cost. Before the subdistrict court, parties may conduct their own case, and a company may be represented by its own director or by an authorised agent. Before the district court, representation by a lawyer is mandatory. The common claim that a writ of summons must always be drafted by a lawyer is wrong, and it discourages small creditors from pursuing perfectly good claims.
How do the proceedings run?
The proceedings begin with a writ of summons (dagvaarding) setting out the claim, the grounds and the evidence, which a bailiff serves on the debtor. If the debtor does not appear, the court gives judgment in default. It grants the claim unless the claim appears unlawful or unfounded. That is why a defective fourteen-day letter still costs the creditor its collection costs even when nobody turns up.
If the debtor appears and defends, there is usually an exchange of written statements followed by an oral hearing. The court then gives judgment (vonnis).
What does it cost, and can you appeal?
Keep three points about cost and risk in mind.
- Court fees are payable in advance by both parties. They depend on the value of the claim and the status of the party, and they are indexed each year. Take the current amounts from the judiciary's published table.
- The losing party is normally ordered to pay the winner's legal costs. However, the lawyer's fees in that order are calculated on a fixed scale and rarely cover what was actually spent.
- A judgment for a small sum may not be open to appeal at all. The Code of Civil Procedure sets a minimum value below which appeal is excluded.
A judgment is normally declared provisionally enforceable. It can then be enforced immediately, even if an appeal is lodged. If the judgment is later overturned, the creditor must repay what it has collected, and it bears the risk that the debtor becomes insolvent in the meantime.
What may a bailiff do to enforce a judgment?
After serving the judgment and a demand for payment, a bailiff may attach wages, bank balances, goods, property and shares. The law protects a minimum income and the goods a debtor needs for daily life.
A judgment becomes enforceable once the bailiff has served the official copy on the debtor. Service is not a formality. It is the moment from which the debtor is on notice and from which short statutory periods begin to run. The bailiff normally serves the judgment together with a demand for payment, and attachment may follow only after that demand has expired.

Which assets can be attached?
The bailiff has a defined toolkit.
- Attachment under a third party (derdenbeslag) catches money that someone else owes the debtor. Typical examples are wages held by an employer, a benefit paid by a public body or a credit balance at a bank. The third party must declare what it holds and pay it to the bailiff.
- Attachment of movable goods allows business inventory, machinery or a vehicle to be seized and sold at public auction.
- Immovable property can be attached and sold through a notary.
- Shares in a company can be attached as well. In a family business this is often more effective than seizing anything physical.
What are the limits on enforcement?
Against those powers, Dutch law sets real limits. A protected earnings threshold, the beslagvrije voet, guarantees the debtor a minimum income that cannot be attached. Since that regime was simplified, the bailiff calculates the threshold from data held in the national income and benefits records, instead of relying on information the debtor supplies. That removed a longstanding source of hardship.
Goods necessary for daily life, such as beds, clothing, food and the tools a debtor needs to earn a living, cannot be seized at all. There is no imprisonment for inability to pay a money debt. Coercive detention exists in Dutch law only in narrow circumstances and not as a general collection measure.
Where the debtor has several creditors, the bailiffs coordinate through a central attachment register, and a coordinating bailiff distributes what is collected. A creditor who joins late in a queue on a modest salary may recover nothing for years. That is a reason to assess recoverability before starting proceedings, not after winning them. A debtor who believes enforcement is being carried out unlawfully also has remedies, as our article on legal remedies against enforcement of a judgment explains.
How do you collect across borders within the EU?
A judgment from one EU member state can be enforced in another without a separate declaration of enforceability. For the claim itself, European procedures are often simpler than a national route.
This matters for creditors based outside the Netherlands and for Dutch creditors with foreign debtors. Under the Brussels I bis Regulation, a judgment given in one member state is recognised and enforced in the others without an intermediate exequatur procedure. A Dutch judgment can be handed straight to a bailiff elsewhere in the Union, and a foreign judgment to a Dutch one.
Two simplified procedures exist for the claim itself. The European order for payment is a written procedure for uncontested cross-border money claims, in which the court issues an order on the basis of a standard form. If the debtor objects, the case continues as ordinary proceedings. The European small claims procedure handles low-value cross-border claims largely in writing and without compulsory legal representation. In addition, the European account preservation order allows a creditor to freeze a debtor's bank account in another member state, on conditions comparable to Dutch prejudgment attachment.
What if there is nothing left to collect?
Bankruptcy and restructuring procedures usually leave an unsecured creditor with little. If a debtor has ceased to pay and there is more than one creditor, you can petition for its bankruptcy under the Bankruptcy Act, but once bankruptcy is declared, the trustee takes over and individual enforcement stops. Our overview of the Bankruptcy Act and its procedures sets out how the estate is administered.
A business in difficulty may also propose a restructuring plan that the court confirms and that binds dissenting creditors; see our article on the WHOA restructuring scheme. For an individual debtor, the statutory debt rescheduling scheme (Wsnp) leads to a halt on enforcement. A search of the trade register, the land registry and the register of attachments shows in an afternoon whether there is anything to recover.
What should you check as a creditor?
- That the payment term and your general conditions were agreed in writing and actually provided before delivery, because conditions that were not provided can be annulled (Article 6:233 BW).
- That the debtor is in default, by a notice of default or because a fixed payment date has passed (Articles 6:82 and 6:83 BW).
- Against a consumer: that your fourteen-day letter gives fourteen days from the day after receipt and states the costs.
- That any collection agency you instruct is in the Justis register of debt collection services.
- The five-year limitation period, and that every interrupting demand is in writing (Articles 3:307 and 3:317 BW).
- Whether the debtor has assets, via the trade register and the land registry, before you start proceedings.
What should you check as a debtor?
- Whether the claim is correct and whether the goods or services were actually delivered; dispute it in writing and with reasons.
- Whether you received a valid fourteen-day letter before collection costs were charged, if you are a consumer.
- Whether the collection agency is registered with Justis.
- Whether the claim is older than five years without a written interruption, and therefore time-barred.
- After an attachment of wages: whether the bailiff has applied the correct protected earnings threshold (beslagvrije voet).
What can we do for you with debt collection?
Our corporate lawyers assist Dutch and foreign creditors, and debtors facing a claim. We can:
- review your file, contract and general conditions and assess whether the claim is provable and recoverable;
- draft a notice of default or a fourteen-day letter that meets Article 6:96 BW;
- apply to the interim relief judge for leave for prejudgment attachment;
- draft the writ of summons and conduct the proceedings before the subdistrict court or district court;
- instruct a bailiff to enforce the judgment, or choose a European procedure for a debtor abroad;
- defend you against an unfounded claim or unlawful enforcement.
Summary
- Interest and collection costs only run once the debtor is in default, usually after a written notice of default (articles 6:82 and 6:83 of the Civil Code).
- Against a consumer, collection costs require a correct fourteen-day letter; the term starts on the day after receipt (ECLI:NL:HR:2016:2704).
- Since 1 April 2025, collection service providers must be registered with Justis; a bailiff is the only one who can serve a summons and levy attachment.
- Contractual payment claims generally become time-barred after five years, but a written demand interrupts the period (articles 3:307 and 3:317 of the Civil Code).
- Check recoverability before you sue, and consider prejudgment attachment or a European procedure where the debtor or its assets are abroad.
Frequently asked questions
How long does the debt collection process take?
With a cooperative debtor, the amicable phase can be completed within a few weeks. An undisputed court case, often decided in default, adds several months; a defended case can take more than a year from the first demand to judgment, and enforcement can take longer still.
Who pays the debt collection costs?
The debtor generally pays the extrajudicial collection costs, provided the creditor has followed the correct steps. Against a consumer, the costs are capped by a decreasing percentage of the principal with a minimum of €40, and they are only due after a compliant fourteen-day letter under Article 6:96 BW.
Can I dispute a debt during the collection process?
Yes, at any time. Do so in writing, as early as possible, and explain why: the amount is wrong, the delivery was defective or there is no debt. The creditor then has to prove the claim in court, and your written objections form the basis of your defence.
What is the difference between a debt collection agency and a bailiff?
A collection agency (incassobureau) works only in the amicable phase and has no power to force payment. A bailiff (gerechtsdeurwaarder) is a public official who alone may serve a writ of summons and, after a judgment, attach wages, bank accounts and assets.