Asset freezing in the Netherlands is done through conservatoir beslag, a protective attachment governed by Book 3 of the Code of Civil Procedure. A creditor applies to the preliminary relief judge for leave, without notifying the debtor, and leave is commonly granted within one or two working days on a summary review of the claim. The attachment secures assets pending the outcome; it does not decide the dispute, it does not create priority over other creditors, and the creditor bears the risk if the claim is ultimately dismissed.
What a pre-judgment attachment is, and what it is not

A conservatory attachment freezes an asset so that it is still there when a judgment arrives. It is a preservation measure, not an enforcement measure: the creditor cannot sell the asset, cannot have the frozen money paid out and does not obtain any right to the asset itself. Once the creditor holds an enforceable judgment, the conservatory attachment converts into an executory attachment by operation of law, without a fresh procedure, and only then does realisation become possible.
Three limitations follow from that nature and are worth stating at the outset, because they are the points on which expectations most often go wrong.
An attachment gives no preference. The attaching creditor does not move ahead of other unsecured creditors; if several creditors attach the same asset, they share in proportion to their claims, subject to any genuine security interests such as a mortgage or a pledge that rank ahead of all of them. If the debtor is declared bankrupt, conservatory attachments lapse and the creditor is left with an ordinary claim in the insolvency. Our guide on bankruptcy in the Netherlands explains what happens to a secured position at that point.
An attachment on a bank account catches a moment, not a flow. When the bailiff serves the order, the bank freezes the balance standing to the account at that moment, up to the amount for which leave was granted. Sums credited afterwards are not caught. A debtor whose account is emptied on the day before the attachment loses nothing, which is why timing and asset tracing matter more than the size of the claim.
And an attachment is levied at the creditor’s own risk. Under settled Supreme Court case law, a creditor whose claim is ultimately dismissed has as a rule acted unlawfully by attaching, and is liable for the damage the attachment caused, without the debtor having to show fault. That liability is the counterweight to a procedure in which the debtor is not heard.
The terms you will encounter
| Term | What it means | Role in the procedure |
|---|---|---|
| Beslagrekest | The written petition for leave to attach. | Filed by a lawyer; sets out the claim, the grounds and the assets to be frozen. |
| Voorzieningenrechter | The preliminary relief judge of the district court. | Reviews the petition summarily and grants or refuses leave. |
| Beslagverlof | The leave to attach. | Fixes the amount for which attachment may be levied and the deadline for starting the main action. |
| Beslagene | The debtor whose assets are frozen. | Not heard before leave is granted; challenges the attachment afterwards. |
| Derde-beslagene | A third party holding assets of or owing money to the debtor, such as a bank or a customer. | Must freeze what it holds and file a formal declaration of what it holds. |
| Gerechtsdeurwaarder | The court bailiff. | The only official who may levy the attachment and serve the documents. |
What the court requires before granting leave
The preliminary relief judge grants leave on two conditions: the claim must be summarily plausible, and there must be a genuine ground to fear that assets will otherwise disappear. Neither is examined in depth, but neither is a formality.
The petition must set out the claim clearly: what the debtor owes, on what legal basis, and how the amount is calculated. Supporting documents are attached, typically the contract, the invoices, the correspondence and any acknowledgement of the debt. The judge does not hear evidence and does not decide the merits; the test is whether the claim is plausible on the face of the papers. A claim that is contested on grounds the petition does not mention is a claim the judge cannot assess properly, which brings us to a duty that is easy to underestimate.
An applicant in an ex parte procedure is under a duty of complete and truthful disclosure. In practice that means the petition must set out the defences the debtor has already raised, any counterclaim, any earlier attachment attempts and any relevant proceedings elsewhere. Concealing a known defence is the single most reliable way to have an attachment lifted, and it exposes the creditor to a costs order and a damages claim. The national guidance applied by the courts is explicit on this point, and judges do check.
The fear of dissipation
The second requirement is a real risk that recovery will be frustrated. The judge asks whether there are concrete facts pointing that way, not whether the creditor feels uneasy. Facts that carry weight include a pattern of non-payment and broken payment arrangements, transfers of assets to related parties or to entities abroad, a restructuring that moves the business out of the contracting entity, signs of financial distress such as other creditors suing or filings being late, a debtor who has stopped responding altogether, and a debtor whose only connection with the Netherlands is a bank account or a movable asset.
Two qualifications matter. First, the threshold is applied less strictly than the wording suggests, and a well-documented history of non-payment is often enough; the Dutch system is genuinely creditor-friendly on this point. Second, that is not a licence for a bare assertion. Where the petition offers nothing but the fact that the invoice is unpaid, leave is refused or granted for a lower amount.
The judge fixes the amount for which attachment may be levied, generally the principal claim increased by a percentage for interest and costs, and may impose conditions. The court can require the creditor to provide security for the damage the attachment may cause, and does so more readily where the creditor is established outside the jurisdiction or where the attachment is likely to be disruptive. In certain categories, including attachments affecting a debtor’s home and cases where the claim is evidently disputed, the judge may decide to hear the debtor before ruling, which removes the element of surprise but produces a far more robust order.
The procedure step by step
The sequence is short and the deadlines are unforgiving.
A lawyer files the petition with the preliminary relief judge of the district court, in the district where the assets are located or where the debtor is domiciled. The judge decides on the papers, usually within one or two working days, sometimes the same day where urgency is demonstrated. The leave states the amount, identifies the assets or the third parties concerned, and sets the deadline for instituting the main action.
The bailiff then levies the attachment. For a bank or a customer, that means serving the order on the third party, which must freeze what it holds and, in due course, file a declaration setting out exactly what that is; the statutory period for that declaration runs to four weeks from the attachment. For real estate, the bailiff registers the attachment with the Land Registry, after which the property cannot be sold or mortgaged free of it. For movable property, the bailiff attends and draws up an inventory. The debtor is served with the documents at the same time or shortly afterwards, and only then learns what has happened.
The main action must follow. The leave sets the period, which by statute is at least eight days after the attachment and in practice is commonly fourteen days, and the creditor must institute proceedings on the merits within it, by writ of summons, by petition or by commencing arbitration. Exceeding the period causes the attachment to lapse automatically. The period can be extended, but only on a request made before it expires, so the date belongs in the diary on the day leave is granted.
Once judgment is obtained and is enforceable, the conservatory attachment becomes executory without a further application, and the bailiff can proceed to collection or sale. Between those two moments the attachment simply holds the position; that is its entire function.
Which assets can be frozen

In principle anything belonging to the debtor that has economic value can be attached, subject to a limited set of statutory exemptions. The practical question is not what is possible but what is effective, because each type of asset behaves differently once frozen.
Bank accounts are the usual first target. The freeze is immediate and the pressure is real, but as noted it catches only the balance at the moment of service. Attaching the account of a natural person is subject to the statutory protected minimum, so that a debtor is not left without means of subsistence. Serving on several banks at once is possible, and is often sensible where the banking relationship is unknown, though a scattergun approach across accounts that turn out to be empty adds cost without effect.
Real estate is the most durable form of security. Registration at the Land Registry blocks sale and further mortgaging, and the attachment stays in place indefinitely until the claim is resolved. Where the property is already mortgaged to the hilt the economic value of the attachment may be nil, so check the register before spending on it.
Receivables owed to the debtor by third parties are the most disruptive. Serving the order on the debtor’s own customers intercepts incoming cash and, unavoidably, tells those customers that their supplier is in dispute. That reputational effect is exactly why the measure works and exactly why it is challenged; a receivables attachment that turns out to be unfounded is the classic case in which serious damage is claimed.
Shares in a Dutch BV or NV can be attached by serving the order on the company, which then may not cooperate in a transfer. This is a powerful measure in shareholder disputes and in claims against a holding structure, and it carries its own procedural complications; our article on the attachment of shares deals with them.
Movable business assets such as vehicles, machinery and stock can be attached at the location where they are found, provided they belong to the debtor; goods delivered under retention of title belong to the supplier and cannot be attached for the debtor’s debt. Registered intellectual property rights can be attached through the relevant registers. Attachment is also available for purposes other than securing a sum of money: to secure delivery of a specific asset, to preserve evidence, and in a matrimonial context to preserve the estate pending a division.
Comparison of attachable assets
| Asset | How it is attached | What to watch |
|---|---|---|
| Bank account | Order served on the bank; declaration follows within four weeks. | Only the balance at the moment of service is caught; protected minimum for individuals. |
| Real estate | Registration with the Land Registry. | Check existing mortgages first; the equity may already be gone. |
| Receivables | Order served on the debtor’s customers. | Highly effective and highly damaging; the damages exposure is correspondingly large. |
| Shares | Order served on the company whose shares they are. | Blocks transfer; voting and dividend rights need separate attention. |
| Movable goods | Bailiff attends and records an inventory. | Retention of title and third-party ownership defeat the attachment. |
| Registered IP rights | Entry in the relevant register. | Effective where the value of the business sits in its portfolio. |
The debtor’s position and how to challenge an attachment
A debtor who finds an account frozen is not without remedies, and the routes are quick. The principal one is summary proceedings before the preliminary relief judge to have the attachment lifted. The statutory grounds are broad: the attachment is lifted if the formalities were not observed, if the claim relied on appears summarily to be unsound, if the attachment is unnecessary, or if sufficient alternative security is provided. Because the procedure is summary, the judge weighs the interests on both sides, and the debtor who can show concrete and disproportionate harm has a real chance even where the claim is not obviously bad.
Alternative security is the cleanest route. If the debtor offers sufficient security, in practice a bank guarantee for the amount of the leave in the standard wording used in Dutch commercial practice, the attachment must be lifted. The creditor keeps the security it was entitled to, the debtor regains the use of its assets, and the dispute proceeds on the merits without the collateral fight. Where a business is being disrupted, this is normally the fastest and least expensive outcome.
The other arguments worth developing are excess and disclosure. An attachment levied for far more than the claim can support, or spread across many more assets than are needed to secure it, is disproportionate and can be reduced or lifted. And where the petition failed to disclose a known defence or a material fact, that alone can be enough. Our article on lifting a conservatory attachment sets out how those arguments are constructed, and the glossary entry on preliminary relief proceedings explains how the procedure runs.
Finally there is the damages claim. If the main claim is dismissed, the creditor is in principle liable for the loss the attachment caused, and that loss is not limited to interest on the frozen sum: lost contracts, extra financing costs and, where a receivables attachment reached customers, reputational damage can all be claimed. A debtor who intends to pursue that should document the harm as it occurs rather than reconstructing it afterwards.
Related forms of attachment
Not every attachment is aimed at securing a sum of money, and the Code of Civil Procedure provides several variants that are easy to overlook.
Attachment to secure delivery is available where the claim is not for money but for a specific asset: goods sold but not delivered, a company’s administration held by a former director, artwork, a vehicle. The asset is frozen where it is found, so that it can be handed over if the claim succeeds. The same route can be used to secure a claim to the transfer of registered property or of shares.
Evidentiary attachment allows documents and data to be secured where there is a real risk that they will disappear. The material is taken into custody by the bailiff, usually a sequestrator, and is not handed to the applicant; access follows only from a separate claim for inspection of specified documents in which the applicant has a legitimate interest. The distinction matters: the attachment preserves, it does not disclose, and an applicant who treats it as a search of the opponent’s files will be refused. This route is used in fraud investigations, in disputes about breach of confidentiality and in intellectual property cases, where it has its own statutory basis.
Attachment in one’s own hands is available where the creditor itself owes the debtor money, for instance where both parties have claims under the same contract. Rather than paying and then trying to recover, the creditor attaches the sum in its own hands, which neutralises the payment obligation pending the outcome. In family matters an attachment is available to preserve the marital estate while a division is pending, which prevents assets being moved out of the community before the court rules on it.
Each of these requires the same leave from the same judge, on the same two conditions, and each is subject to the same rule that the main action must follow within the period set. The difference lies in what is being secured, and choosing the right variant at the outset avoids having to start again.
After the attachment: declarations, release and collection
An attachment on a third party is only half a measure until the third party says what it holds. A bank, a customer or an employer served with an attachment must file a declaration setting out the debtor’s assets and debts in its hands, and the statutory period for doing so runs to four weeks from the attachment. A third party that fails to declare, or that declares incompletely, can be compelled to do so in separate proceedings and may end up being ordered to pay the creditor’s claim as if it owed it, which is a sanction third parties take seriously once it is explained to them.
The declaration is also where the creditor finds out whether the attachment was worth levying. A declaration of nil on a bank account, or a customer stating that the invoice was already paid, ends the exercise for that asset and the attachment is best released rather than left in place, since maintaining an attachment that plainly secures nothing contributes to a later damages claim.
Release can happen in several ways. The creditor can lift the attachment voluntarily, which is done by the bailiff and should be recorded. The parties can agree a release against payment or against security as part of a settlement. The court can order a release in summary proceedings. And the attachment lapses by operation of law where the period for the main action is missed, where the claim is finally dismissed, or where the debtor is declared bankrupt.
If judgment is given in the creditor’s favour, no fresh attachment is needed. The conservatory attachment becomes executory once the judgment is served, and the bailiff can then require the third party to pay over what it holds, or proceed to a sale of the attached goods or, for real estate, to a forced sale through a notary. That final phase has its own rules and its own timetable, and it is generally worth trying to convert a successful attachment into a payment arrangement before entering it.
Strategy: when an attachment is worth levying
An attachment is a means, not an end, and the decision to use one should follow an assessment of what it will actually achieve. Three questions settle it.
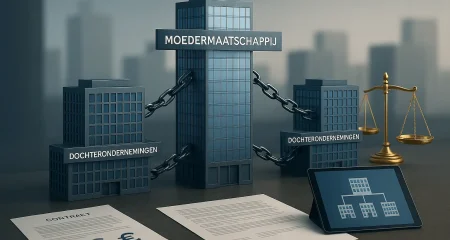
The first is what there is to freeze. Asset tracing comes before the petition, not after. Public sources answer a surprising amount: the Chamber of Commerce register shows the corporate structure, the annual accounts show whether the entity you are suing has any substance, the Land Registry shows property and the mortgages on it, and the vehicle and vessel registers show registered movables. Where the trading entity is an empty shell in a group, the attachment is better aimed at the entity that holds the assets, which raises the separate question of whether you have a claim against that entity at all.
The second is what the attachment will cost, in money and in relationship. There are court fees, bailiff’s fees for each attachment levied and served, and legal costs, and the creditor pays them upfront with no guarantee of recovering them. If the claim is dismissed, add the damages exposure. Against a counterparty you still trade with, an attachment usually ends the commercial relationship the day it is served.
The third is what happens next. An attachment obliges you to litigate: the main action must be started within the period set. A creditor who is not ready to run that case, or not prepared to fund it, should not levy the attachment. Used well, though, the measure changes the dynamic of a dispute completely: a debtor who has ignored demand letters for months tends to engage within days of an account being frozen, and a substantial proportion of attachment files end in a settlement rather than a judgment. Our guide to debt collection in the Netherlands sets out the steps that normally come before this one.
For debtors, the mirror-image lesson is that the measure is easiest to defend against before it happens. Answer demand letters, document any genuine dispute in writing at the time, keep the corporate housekeeping in order, and take advice as soon as a claim is threatened. A documented, substantiated defence on file is the material a lawyer needs to argue that the claim is summarily unsound, and it is the disclosure the creditor will then have to put before the judge.
Cross-border use of Dutch attachments

The Netherlands is frequently used to secure assets in disputes that are being litigated elsewhere. A Dutch court can grant leave to attach assets located in the Netherlands even where it has no jurisdiction over the merits, and the Code of Civil Procedure expressly contemplates that the main action is brought abroad. For a foreign creditor whose debtor holds a Dutch bank account, real estate or shares in a Dutch company, that is a genuinely useful route, and it is one reason the Netherlands appears so often in international recovery strategies.
Two European instruments frame the position. The Brussels I recast Regulation governs jurisdiction and the circulation of decisions within the European Union, and it allows a creditor to apply for provisional measures to the courts of a member state even where another member state’s courts hear the merits. It contains an important limitation: a protective measure ordered without the defendant being summoned circulates under the Regulation only if the decision was served on the defendant before enforcement. A Dutch attachment therefore secures Dutch assets very effectively, but it is not an instrument for freezing assets in another member state.
For bank accounts specifically, the European Account Preservation Order fills that gap. It allows a creditor in a cross-border case to obtain, from the court of one member state, a single order freezing the debtor’s bank accounts in other participating member states. It is available before, during and after proceedings on the merits, it is granted without hearing the debtor, and it comes with its own safeguards: the applicant must generally provide security, the creditor is liable for damage caused by an unjustified order, and there is a mechanism for obtaining account information where the creditor does not know where the debtor banks. Denmark does not participate. The Order and the Dutch domestic attachment are alternatives, and which is preferable depends on where the accounts are and how much is known about them.
Once judgment is obtained, recognition and enforcement become the issue, and the answer differs sharply depending on whether the judgment comes from an EU member state, from a state party to a relevant convention, or from elsewhere. Our article on the recognition and enforcement of foreign judgments deals with that, and the piece on international debt collection covers the practical route.
Frequently asked questions
How quickly can assets be frozen in the Netherlands?
Leave is commonly granted within one or two working days of the petition being filed, and the bailiff can levy the attachment the same day the leave is issued. Where genuine urgency is set out and documented, a decision on the same day is possible. The speed comes from the fact that the judge decides on the papers without hearing the debtor; the preparation, in particular the asset tracing and the assembly of the supporting documents, is what actually takes the time.
Does the debtor get to respond before the attachment?
As a rule, no. The petition is dealt with without the debtor being notified, which is what prevents assets being moved in the interval. The debtor learns of the attachment when the bailiff serves the documents and can challenge it immediately afterwards in summary proceedings. In defined categories the judge may nevertheless decide to hear the debtor first, in particular where the attachment concerns a home or where it is apparent from the file that the claim is seriously disputed.
What happens if the attachment turns out to be wrongful?
The creditor levied it at its own risk. If the claim on which the attachment was based is ultimately dismissed, the creditor is in principle liable for the damage the attachment caused, and the debtor does not have to prove that the creditor was at fault. The damage can extend well beyond interest, to lost contracts, additional financing costs and reputational harm where third parties were served. This is the main reason to test the strength of a claim honestly before attaching, and to disclose the known defences in the petition.
Does an attachment give me priority over other creditors?
No. A conservatory attachment secures the asset but creates no ranking. Several attaching creditors share the proceeds in proportion to their claims, behind any mortgage, pledge or statutory preference. If the debtor is declared bankrupt, the attachment lapses and you become an ordinary creditor in the insolvency. Where insolvency is a realistic prospect, a security right agreed in advance is worth far more than an attachment levied afterwards.
Can I attach for a claim in a foreign currency?
Yes. The claim may be denominated in any currency; state the amount in the original currency in the petition and add an indicative euro equivalent with the conversion basis, because the leave will fix a euro amount for the attachment. The same applies to interest and costs, which are added as a percentage of the principal when the amount of the leave is fixed.
How long does an attachment last?
Until the claim is resolved, provided the main action is brought within the period set in the leave and is then pursued. The attachment lapses automatically if that period is missed, if the claim is dismissed by a final judgment, if sufficient security is provided, if the court lifts it, or if the debtor is declared bankrupt. There is no separate expiry date, and a real estate attachment can therefore remain registered for years while proceedings run.
Law and More acts for creditors and debtors in attachment matters in the Netherlands: asset tracing and the preparation of the petition, obtaining leave and instructing the bailiff, the main proceedings that must follow, and summary proceedings to lift an attachment or to have security substituted for it. The measure works best when it is prepared properly and used at the right moment. If you are considering an attachment, or your assets have just been frozen, please contact us promptly, because in this area the deadlines are short.